 Apparel and workwear
 Building supplies
 Medical supplies
 Fitness equipment
 Energy and power
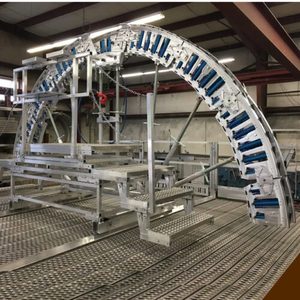 Industrial equipment
 Livestock supplies
 Mining supplies
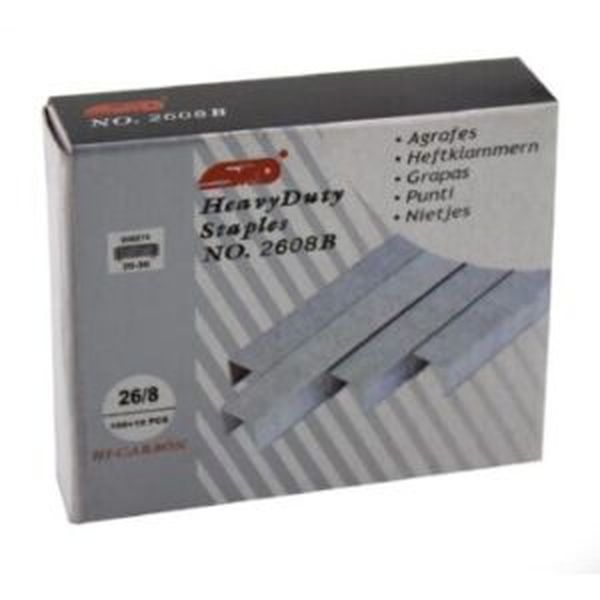 Stationery supplies
 Events and catering equipment

Every diamond downturn before this one ended; the worry now is that this one is partly structural. Global natural-diamond demand has remained weak while lab-grown alternatives continue to gain share. For Botswana, whose budget and economy are built on natural stones, that combination is more troubling than a simple cyclical dip, because it raises the possibility that the market is being reshaped rather than merely paused. A cycle is something you wait out; a redefinition is something you respond to.
The distinction is the whole point, and getting it right is the first task for a producer nation. A cyclical downturn reflects cautious consumers who will return when confidence does. A structural shift in what buyers will pay for, and in what counts as an acceptable substitute, does not reverse when sentiment improves. Botswana's challenge is to read which of the two it is facing, knowing the honest answer is probably some of both, and to act on the part that will not simply fix itself.
Weak Demand and a New Competitor at Once
Two forces are pressing on natural diamonds at the same time, and they call for different responses. Soft global demand reflects cautious consumers in key markets, while weak natural-diamond demand coincides with lab-grown alternatives taking share. The first is cyclical and should ease as confidence returns; the second is a durable change in the competitive landscape that a recovery in sentiment will not undo.
This is the first part of the article. The full article is on Cabanga Magazine, from the publishers of the regional business magazines in Africa.
Read the full article on Cabanga Magazine